Medicare Advantage
Part C plans that bundle hospital, medical and often drug coverage. I compare networks, drug tiers and out-of-pocket maximums so the plan actually fits your doctors and prescriptions.
Independent Agent · Licensed & Certified
I am an independent licensed health insurance agent — not an agency. That means you talk to me every time, and I compare plans from multiple carriers to find the coverage that actually fits your situation and your budget.
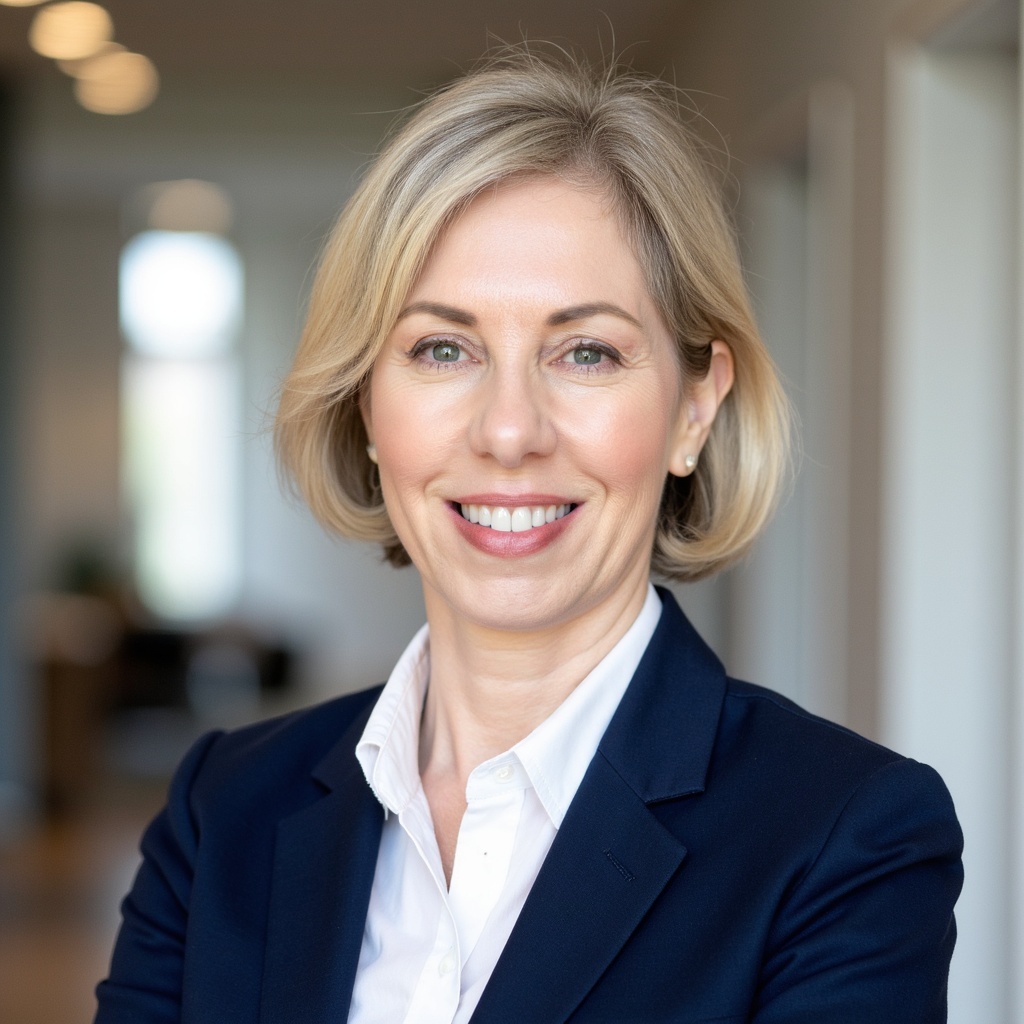
I am an independent licensed health insurance agent based in Pensacola, Florida. I am not an agency and I do not work for a single insurance company — I work for the people who hire me.
That independence matters. Because I am appointed with multiple carriers, I can put their plans side by side and show you honestly what each one covers, what it costs, and where the trade-offs are. Then you decide, with no pressure and no sales script.
Whether you are turning 65, leaving employer coverage, shopping the ACA marketplace, or simply unsure whether the plan you have is still the right one, my job is to make the decision clear.
— Nancy DiRienzo, Independent Licensed Health Insurance Agent
Every plan below is reviewed across the carriers I am appointed with, so the recommendation you get is based on your needs — not on one company’s product list.
Part C plans that bundle hospital, medical and often drug coverage. I compare networks, drug tiers and out-of-pocket maximums so the plan actually fits your doctors and prescriptions.
Plans that pay the gaps Original Medicare leaves behind. I walk you through what each lettered plan covers and what it realistically costs over time.
Standalone prescription drug plans. I run your actual medication list against each plan so you can see the true annual cost, not just the premium.
Individual and family coverage through the Health Insurance Marketplace, including subsidy eligibility and Special Enrollment Periods.
Standalone plans that cover what most medical policies do not — routine dental, eyewear and hearing aids.
Hospital indemnity insurance and accident insurance are complementary supplemental plans that pay cash benefits directly to you to help cover out-of-pocket costs when you are sick or injured.
A captive agent can only offer one company’s plans. A call center hands you to whoever picks up. I am neither.
I am appointed with several insurance companies, so I can compare their plans against each other instead of steering you toward the only one I carry.
This is a one-person practice. There is no call queue and no rotating rep — you get me, before you enroll and long after.
My guidance is free to you. Carriers pay me the same regardless of which plan you choose, so there is no incentive to push one over another.
Claims questions, a new prescription, a doctor leaving the network — those do not wait for October. Neither do I.
I hold an active health insurance producer license in the states listed below and can help residents of any of them.
Adding a state? Ask — I may already be licensed there or able to become licensed quickly.
Certification is not a one-time badge. I complete it every year so the guidance I give reflects the current plan year, the current rules and the current compliance standards.
A call or meet. You tell me your doctors, prescriptions, budget and what has been working and not working with your current plan.
I run your details against the plans available to you from every carrier I represent, and show you the real differences side by side.
You pick the plan that makes sense. I handle the enrollment paperwork and stay your point of contact afterward.
I am an individual, independent licensed health insurance agent — not an agency. When you call, you reach me directly, and I am the person who handles your plan review, your enrollment and your questions afterward.
A captive agent can only sell plans from the single company that employs them. As an independent agent I am appointed with multiple carriers, so I can compare their plans against one another and recommend the one that fits you rather than the one I am required to sell.
Nothing. There is no fee for my help. Insurance carriers compensate agents directly, and your premium is the same whether you enroll through me or on your own.
Most people can make changes during the Annual Enrollment Period from October 15 to December 7, with coverage starting January 1. There is also a Medicare Advantage Open Enrollment Period from January 1 to March 31, plus Special Enrollment Periods triggered by events like moving or losing other coverage. Ask me and I will tell you which window applies to you.
About three months before your 65th birthday. Your Initial Enrollment Period runs from three months before the month you turn 65 through three months after, and starting early keeps you from being rushed or hit with a late-enrollment penalty.
That is exactly what I check before recommending anything. I run your doctor list against each plan’s network and your medication list against each plan’s formulary, so you see the real annual cost rather than just the premium.
A plan review takes about fifteen minutes and costs nothing. If your current coverage is already the best fit, I will tell you that too.
Send a message or call directly. I answer my own phone, and I will get back to you the same business day whenever possible.
Nancy DiRienzo is an independent licensed health insurance agent based in Pensacola, Florida. She is licensed in Florida and Alabama. She is an individual agent, not an agency, and is appointed with multiple insurance carriers, which allows her to compare Medicare Advantage, Medicare Supplement (Medigap), Medicare Part D, ACA marketplace, dental, vision, hospital indemnity and accident plans on behalf of her clients. She holds NABIP Medicare, Medicare Products and Fraud, Waste and Abuse certifications, the Federally Facilitated Marketplace (FFM) certification and AHIP certification, and provides her guidance at no cost to the client. She can be reached at 850-466-7646.
Licensed in: Florida, Alabama.
Contact: 850-466-7646, nancy@mycoverageexpert.com.